
So, I don’t typically write about my personal finances online. I’m retired, not affluent, but getting by, living pretty low on the hog, usually no complaints.
BUT.
My solvency rests on a couple of pillars that I have in common with many millions of Americans. Three pillars, really:
– Social Security.
– Medicare. And . . .
– Pretty good health (for my age, yada yada).
I’ll skip the health stories; but have to mention the pills. I currently take a dozen a day; they’ve been holding up the health pillar.
Only one med (so far) is really expensive, and the heart doc says I’ll be taking them til the end.
I can afford it now because of the second pillar: Medicare. particularly its Part D. (For young ‘un readers, it’s the part of Medicare that covers some drug costs. They collect a separate premium for it, deducted from the first pillar, Social Security.)
When I started Social Security (2012), the Part D monthly drug premium was about $70, as I recall.
Since then, over 14 years, it’s gone up. Crossed into 3-figures after several years. That’s life.
No it’s not. It’s inflation. Price-gouging. Don’t get me started.
 And right now it’s the concrete personal impact from what 47 called his Big Beau—[can’t bear to say that word here] Bill, passed on Independence Day 2025, ruining the national holiday. The BBB’s full havoc was delayed til after Midterm elections, just a few weeks from now.
The havoc, yes. But the bill, aka invoice, arrived in my mailbox late last week. I opened it today. And what does it show?
It shows a pillar shaking. Like in an earthquake, or a Hurricane Helene blow & flood.
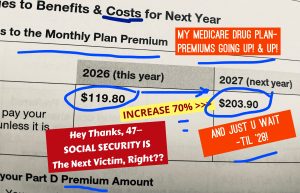
Below is a screenshot of the announcement. It boils down to three numbers:
$119.80
$203.90 and
70: as in percent.
DRUG PLAN PREMIUMS FOR2027:
To sum up:
The monthly premiums this year have been 119.80 .
They will increase in January 2027 to $203.90.
That’s an annual price jump of 70%.
With a promise of more comparable jumps to come.
But wait, there’s more:
Medicare takes back a chunk of each Social Security payment: for Medicare coverage of major medical costs. A second chunk goes to a so-called Medigap policy, to cover most or all of what the major medical doesn’t cover (there’s a lot).
The Medigap policy is optional: you can skip it, and pay the torrent of other medical bills out of your own pocket; good luck.
The bite from my Medigap policy also gets bigger each year; I haven’t yet seen the 2027 number. But it’s big already, and all the omens point toward another jolt of sticker shock when that arrives.
Added up, all these built-in medical charges add up to the biggest single expense category of the benefits from the third pillar, Social Security itself. And that’s when I’m “healthy,” just popping my dozen daily pills and trying to keep some gratitude in the attitude.
In fact, Like millions of others, despite all this “coverage,” I’m only one serious health event — a bone-breaking fall, many kinds of cancer, and the old standbys, cardiac or dementia — from ending my days penniless, with all my modest estate sucked up by the Last Round Medical Financial Complex.
Or less dramatically, I’m one really big drug prescription away from either bankruptcy or pills.
This scenario is not hypothetical. Well over half a million Americans file for personal bankruptcy each year, and medical bills are chronically the number one biggest reason. The totals have been increasingly rapidly since 47 returned, and bills like the one I opened today will spur that poverty epidemic.
Money. I already knew I can’t take it with me. But I’d rather leave some or most to be shared among my progeny; it won’t send anyone to the Ivy League, but they’ll think of something fun or useful.
But what if I stay healthy for several more years?
Then a different health disaster is coming at me — and millions of other Americans:
It’s the virus of geriatric poverty. It’s not really new, but an epidemic of it is coming, the Superspreader for it is 47’s BBB bill — and its inside parallel, Russell Vought”s Project 2025. (There’s no room here for a listing of Vought’s hundreds of impoverishing efforts, but many are well underway.)
The Part D bill I opened with its 70% bigger bite out of the Medicare pillar was the most concrete impact on me personally. It will reduce my 2027 “disposable” income by just under $1000.
But more bites are coming from BBB. And on a broader scale: every month that 47’s wars continue — the one with Iran, and the trade wars with everyone else — they push forward the day when the crisis hits the oldest, and once most solid pillar of my (our) final years, Social Security.
This last is not news, either. In fact many of the well-heeled architects of Project 2025 & BBB have been yearning and scheming for its arrival for decades.
What can be done? Typically columns like this now turn into campaign ads. Here’s my Not-Ready-For-Tik-Tok, quickie:
Step One is to get a new Congress, President & Supreme Court. Step Two is to pick among the numerous available plans to save the pillars.
And Step Three, do it.

There you are.
The Midterms are Door #1.
You figure out how to get through it.
I have to go take some pills.
Then pay some bills.
And go check the mail.